Loading article
Payments, accounts, IBANs, cards and compliance are becoming capabilities embedded directly into platforms. Fintech-as-a-Service turns this invisible infrastructure into a product, operational and competitive advantage.
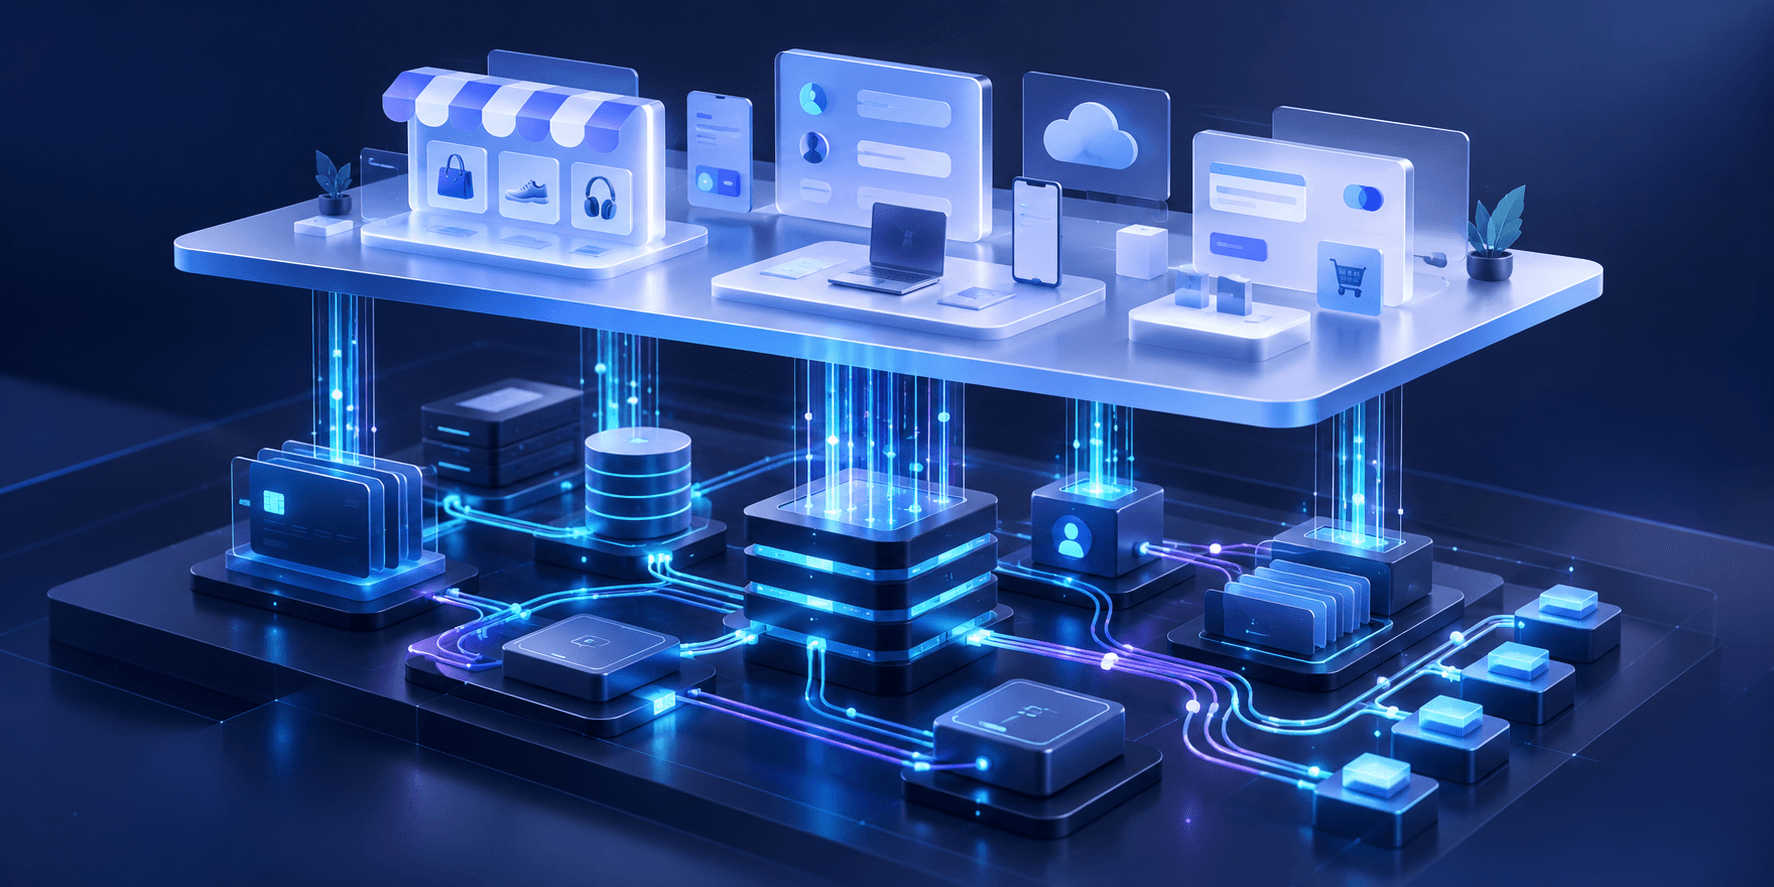
For years, digital platforms differentiated themselves through their business features, user experience, or ability to centralise data. Competition is now shifting towards a less visible but increasingly strategic layer: financial infrastructure.
Payment collection, payment accounts, IBANs, fund distribution, cards, beneficiary verification and automated compliance are no longer necessarily peripheral services. When embedded directly into a platform, they can become part of the user experience and a source of lasting differentiation.
This is precisely the promise of Fintech-as-a-Service: enabling a non-financial company to embed financial services into its product without having to build the entire underlying technological, operational and regulatory infrastructure itself.
Fintech-as-a-Service, or FaaS, is a model in which modular financial infrastructure is made available to a company through APIs, technical components or white-label solutions.
Depending on the requirements and applicable framework, this infrastructure may cover:
payment collection and disbursement;
the opening of payment accounts;
the allocation of IBANs;
card issuance or management;
credit transfers and direct debits;
automated fund distribution;
KYC and KYB;
fraud prevention and anti-money laundering controls;
transaction reconciliation;
and certain interactions with digital assets.
The end user remains within the platform environment. They may not even be aware of the various providers, controls and systems involved in executing the transaction.
The financial service therefore becomes an embedded part of the business workflow, just like managing a project, an order or an invoice.
These three terms are closely related, but they do not describe exactly the same thing.
Banking-as-a-Service generally refers to the provision of banking services or capabilities by an authorised institution, often through APIs.
Embedded finance describes the outcome from the user’s perspective: a financial service is directly accessible within software, a marketplace or a non-financial application.
Fintech-as-a-Service can be understood as the orchestration layer that makes this experience possible. It combines payment capabilities, technical interfaces, compliance, management tools and, depending on the chosen model, several regulated partners.
In practice, terminology matters less than the chosen architecture. A relevant integration must clearly establish:
who provides the regulated service;
who holds or safeguards the funds;
who performs the compliance checks;
who handles incidents;
who owns the contractual relationship;
and which responsibilities remain with the platform.
A visible feature can be copied. A properly embedded financial infrastructure is far more difficult to replicate.
It relies on a combination of technology, compliance, operational procedures, partners, data governance and incident-handling capabilities. This depth creates a form of differentiation that may be less striking than a new interface, but potentially more defensible.
The platform no longer merely helps users manage their business. It also enables them to execute the financial flows associated with it.
A marketplace can, for example, collect a payment, identify the beneficiaries, calculate a commission and then distribute the funds. Management software can automatically match a payment with an invoice. An industry-specific platform can offer a payment account and payment methods suited to its users.
The product no longer stops at managing information: it supports the execution of the transaction itself.
This development changes the platform’s position in the value chain.
When users must leave their software to open their banking interface, initiate a payment, search for a transaction and then reconcile the data manually, the experience remains fragmented. Every interruption increases the administrative burden and the risk of error.
Conversely, when these operations are embedded into business software, the platform can become the main point of entry for managing the activity.
This integration can improve:
the smoothness of user journeys;
the quality and availability of data;
task automation;
visibility over financial flows;
software usage frequency;
and user retention.
The platform becomes more difficult to replace, not because it artificially locks in customers, but because it concentrates more operational value within a consistent environment.
At first glance, connecting a payment API may seem relatively straightforward. However, financial infrastructure involves far more than a technical connection.
It must also take into account:
the regulatory status of the various parties;
customer identification and verification;
anti-money laundering and counter-terrorist financing controls;
the protection and, where applicable, safeguarding of funds;
authentication;
fraud and dispute management;
system security;
transaction monitoring;
reporting;
business continuity;
and complaint handling.
European regulation is also continuing to foster a more integrated, faster and more secure payments market. The instant payments framework introduces new requirements concerning availability, pricing and verification of the payee. These developments reinforce the value of an architecture capable of keeping pace with regulatory and operational changes in the market. The European Central Bank outlines the main requirements applicable to instant payments.
For a platform, building everything in-house therefore means committing substantial resources to expertise that is not always central to its competitive advantage.
Fintech-as-a-Service makes it possible to share part of this complexity. It does not remove the platform’s obligations, but it can help identify, allocate and embed them from the design stage of the user journey.
The market has sometimes reduced embedded finance to a catalogue approach: one API for payments, another for KYC, and a third for accounts or cards.
This approach quickly reaches its limits. As the number of providers increases, the platform must manage more interfaces, contracts, data formats and overlapping responsibilities.
The real value of Fintech-as-a-Service infrastructure therefore lies less in the number of APIs offered than in its ability to orchestrate the entire system.
A robust architecture must ensure:
Functional consistency
Financial services must address the actual use case rather than being added as isolated modules.
Regulatory consistency
Each role must be defined: service provider, distributor, potential agent, subcontractor or technology partner.
Data consistency
Information collected during onboarding, checks and transactions must flow securely and remain usable.
User experience consistency
Compliance requirements must be embedded into the journey without creating disproportionate friction.
Operational consistency
The platform must know who steps in when a payment fails, an account is blocked or an additional check is required.
The infrastructure partner thus becomes an architect of financial flows rather than merely a component provider.
As interfaces become standardised and artificial intelligence makes it easier to develop new features, visible differentiation may become less durable.
The depth of the underlying infrastructure then becomes increasingly important.
Two platforms may appear to offer a similar experience. However, the one that best manages onboarding, payments, reconciliation, fund distribution and compliance has a structural advantage.
This capability can enable it to:
reduce manual tasks;
offer shorter user journeys;
gain a better understanding of its users;
create new services;
adapt its revenue model;
and support expansion into new markets more effectively.
Financial infrastructure therefore becomes a product asset. It directly influences the quality of the experience, the economics of the service and the platform’s ability to evolve.
No. Its primary value lies precisely in making capabilities accessible that would otherwise take too long or cost too much to build independently.
A platform does not need to embed a complete suite of financial services from the outset. A phased approach can begin with one clearly identified need:
simplifying payment collection;
automating fund distribution;
offering a payment account;
embedding an IBAN;
accelerating settlement for certain users;
or streamlining the verification of business customers.
The key is to start with the use case and then select the corresponding architecture. Adding financial services without a demonstrated need may, conversely, make the product and its operational framework more cumbersome.
The decision should not be based solely on technical documentation or the stated integration timeline.
Before selecting a solution, a platform should assess at least six dimensions.
Which institution provides the service? In which countries can it operate? Which services is it effectively permitted to provide under its regulatory status?
Can the architecture begin with one initial component and then add others without rebuilding the entire user journey?
Can the provider bring together payments, accounts, onboarding, compliance and flow management around a single use case?
Does the solution preserve an experience that is consistent with the platform’s identity and user journeys?
Do the contracts clearly define each party’s obligations, incident handling and management of the user relationship?
Can the infrastructure support higher volumes, the addition of new services or geographic expansion?
The most suitable partner is not necessarily the one promising the greatest number of features. It is the one offering an architecture that is proportionate, understandable and compatible with the platform’s strategy.
Tractial is developing a Fintech-as-a-Service offering built around complementary components and integrations tailored to its partners’ requirements: payment collection, payment accounts, card programmes and solutions for embedding payment services.
The aim is not to add a generic financial layer to every software product. It is to build an infrastructure with each platform that is consistent with its business, users, financial flows and constraints.
This approach draws on long-standing payments experience and a regulated positioning. Tractial is a payment institution authorised and supervised by the ACPR under reference CIB 16748. The company is also registered in France as a digital asset service provider under number E2023-092. View Tractial’s solutions and regulatory credentials.
The precise combination of services nevertheless depends on the project, user profiles, relevant territories and applicable regulatory assessment.
The future of Fintech-as-a-Service will probably not be determined by how visible the technology is. It will depend on its ability to disappear behind a simple, reliable and consistent experience.
For users, paying, receiving, distributing or reconciling funds should become a natural part of their business software. For the platform, this apparent simplicity will rely on complex, regulated and interconnected infrastructure.
This is where competition is shifting: beneath the interface, in the control of financial flows and in the ability to turn financial infrastructure into a product advantage.
Platforms that anticipate this shift can move beyond their role as management tools to become more comprehensive operating environments. Those that still regard payment as a simple external step may ultimately leave an essential part of the experience and value to other players.
Are you considering embedding payments, payment accounts, IBANs or a card programme into your platform?
Tractial can assess your model, user journeys and financial flows to identify the financial and regulatory architecture best aligned with your project.